A 3 BHK in Shela can look affordable when a broker says, “Sir, only ₹70–80 lakh, EMI will be manageable.”
Then the numbers change.
The quoted price may be ₹75 lakh, but after stamp duty, registration, parking, maintenance deposits, interiors, loan-related costs and other charges, your actual cash requirement can be considerably higher.
I have seen buyers make the same mistake repeatedly: they calculate the EMI first and the total purchase cost later.
That is backwards.
If you are considering a home loan for buying a 3 BHK flat in Shela, your first question should not be:
“How much loan will the bank give me?”
It should be:
“How much property can I safely afford without making my monthly life financially uncomfortable?”
That difference can save you from a 15–25 year financial commitment that looks comfortable on paper but becomes stressful in reality.
This guide focuses on that decision.
It covers loan eligibility, down payment, EMI, hidden costs, RERA verification, property valuation, negotiation, tax considerations and the situations where waiting may actually be smarter than buying immediately.
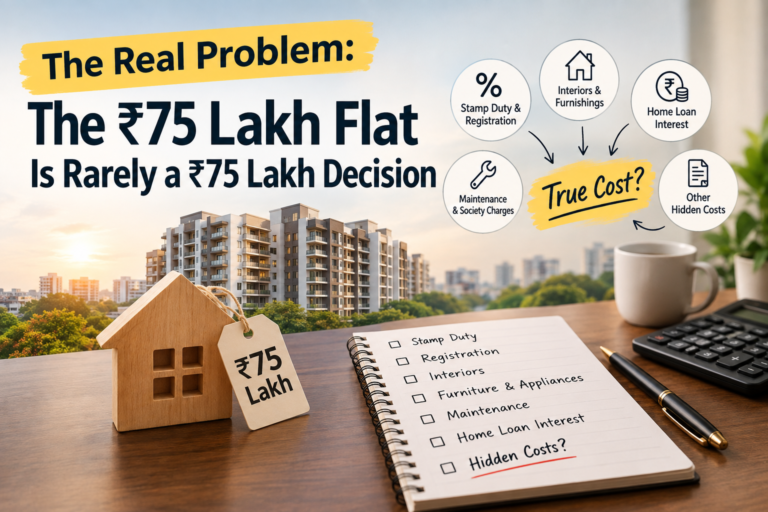
The Real Problem: The ₹75 Lakh Flat Is Rarely a ₹75 Lakh Decision
Imagine a family looking at a 3 BHK in Shela.
The advertised price is:
₹75 lakh
The salesperson immediately starts discussing:
- “Easy home loan”
- “Low EMI”
- “Limited inventory”
- “Price increase next week”
- “Book today to lock the price”
The family starts calculating an EMI.
But they have not yet answered several important questions:
- Is ₹75 lakh the final agreement value?
- Is parking included?
- Are maintenance deposits separate?
- What is the stamp-duty and registration implication?
- Is the quoted area carpet area or built-up/saleable area?
- How much will interiors cost?
- Is the property ready or under construction?
- What happens if possession is delayed?
- Has the lender accepted the property’s valuation?
- Is the buyer’s own income stable enough for the EMI?
- How much emergency savings will remain after the down payment?
This is why online home-loan articles often fail buyers.
They explain how EMI is calculated.
They rarely explain when taking that EMI is a bad idea.
What Is Happening in Shela's 3 BHK Market?
Current online listing data shows that Shela has a very wide range of 3 BHK asking prices.
Housing.com currently shows listings ranging from approximately the ₹60–70 lakh range to ₹1 crore and well above, depending on project, size, construction stage and specification. Its September 2026 listings include examples such as ₹70 lakh, ₹79 lakh, ₹85–91 lakh and ₹94–95 lakh.
Housing.com’s locality data also reports an average 3 BHK apartment rate around ₹5,438/sq ft, with a much wider observed range.
MagicBricks’ Q2 2026 data puts the average asking rate for multistorey apartments in Shela at about ₹5,125/sq ft, with 3 BHK asking rates shown around ₹4,000–₹5,700/sq ft.
These numbers should not be treated as proof that your selected flat is worth that amount.
They are market indicators, not an independent valuation of your property.
That distinction matters enormously when you take a home loan.
Home Loan for Buying a 3 BHK in Shela: Start With Your Own Budget
Before approaching a bank, calculate three numbers:
Number 1: Your maximum comfortable EMI
Do not simply use the maximum EMI a lender says you qualify for.
Your lender is assessing creditworthiness.
You are assessing your future lifestyle.
A household earning ₹1.5 lakh per month may technically qualify for a substantial loan, but that doesn’t mean a ₹70,000–₹80,000 EMI is comfortable.
Consider:
- children’s education
- existing loans
- insurance
- household expenses
- parents’ expenses
- travel
- emergency savings
- retirement investments
- future family plans
A safer approach is to calculate your comfortable EMI after normal household expenses, not before them.
How Much Down Payment Should You Keep?
Suppose the property price is:
₹80 lakh
If your lender finances 80%, a simplified illustration would be:
Loan: ₹64 lakh
Your contribution: ₹16 lakh
But ₹16 lakh is not necessarily your complete cash requirement.
You may also need money for:
- stamp duty
- registration
- documentation
- interiors
- furniture
- appliances
- maintenance deposits
- society-related charges
- moving expenses
- other transaction costs
Therefore, someone with ₹18 lakh in savings should not automatically assume:
“I can buy an ₹80 lakh flat because I need only ₹16 lakh as down payment.”
That leaves almost no financial buffer.
My practical rule
Do not empty your savings account to make the down payment.
A home should improve your financial security, not destroy your emergency fund.
EMI Example for a 3 BHK in Shela
Let’s use an illustrative interest rate of 8.5% purely to understand the mathematics. Your actual rate depends on the lender, borrower profile, loan product and prevailing terms.
Example
Property price: ₹80 lakh
Assumed loan: ₹64 lakh
Assumed rate: 8.5%
Tenure: 20 years
Approximate EMI: ₹55,500/month
Total repayment over 20 years would be roughly ₹1.33 crore, including approximately ₹69 lakh of interest.
That is the number buyers frequently overlook.
A ₹64 lakh loan is not simply a ₹64 lakh decision.
It is a long-term cash-flow decision.
If the interest rate changes on a floating-rate loan, the future repayment structure can also change. This is why buyers should understand their potential EMI changes and review Home loan and EMI planning for a 3 BHK before committing to a long-term loan. RBI’s regulatory framework provides for floating-rate retail loans to be linked to external benchmarks, with reset mechanisms specified in the loan terms.
Always ask the lender:
- What is my benchmark?
- What is the spread?
- How frequently can the rate reset?
- What happens to EMI after a rate increase?
- Can I increase EMI instead of tenure?
- What are the prepayment conditions?
Step-by-Step Buyer Action Plan
Step 1: Select the Right Location Within Shela
Do not buy “Shela.”
Buy a specific micro-location.
Two projects can both have a Shela address and still provide very different:
- road access
- traffic conditions
- school access
- public transport
- grocery access
- drainage
- surrounding development
- construction activity
- daily commute
What to do
Visit the property:
Morning: 8–10 AM
Evening: 6–9 PM
Weekend: once
Don’t rely only on the Sunday site visit arranged by the sales team.
Why it matters
Your commute is a recurring cost.
A ₹3 lakh saving on purchase price can look attractive until you spend years dealing with poor access or a long daily commute.
Mistake to avoid
Do not select a flat simply because:
“This is close to South Bopal.”
Measure the actual travel route and time.
Pro tip
Drive from the project to your:
- workplace
- children’s school
- hospital
- grocery store
during actual peak traffic.
That tells you more than a brochure.
Step 2: Validate the Price Before Applying for the Loan
This is where many buyers lose money.
Suppose the salesperson says:
“₹80 lakh is already discounted.”
Do not accept the statement without checking comparable properties.
Current listings show considerable variation in Shela 3 BHK pricing, even among properties with similar headline configurations.
Mistake to avoid
A large “saleable area” does not automatically mean better value.
Ask for:
RERA carpet area.
Step 3: Verify the Builder and RERA Details
For an under-construction property, do not depend on:
“RERA registered hai, sir.”
Open the project record yourself.
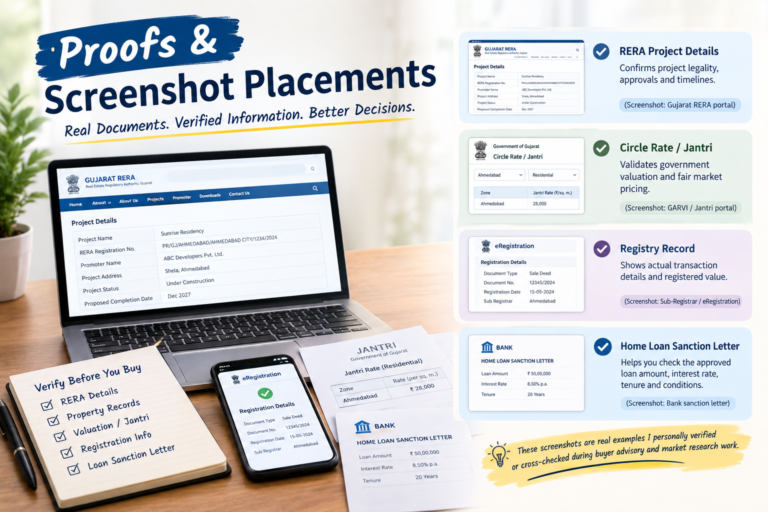
Gujarat RERA’s official portal is the appropriate starting point for checking project information. The state authority’s portal is listed by the Indian RERA portal directory, and Gujarat RERA documentation identifies the official portal as gujrera.gujarat.gov.in.
Check:
- RERA registration number
- promoter name
- project name
- sanctioned details
- declared completion/possession timeline
- registered phases
- quarterly/project updates where available
- complaints/orders where relevant
- land/project details
- apartment configuration
One important warning
RERA registration is not a guarantee that a project is risk-free.
It gives you an important regulatory record to examine.
You still need legal due diligence.
Step 4: Do a Site Visit Like an Inspector
Do not spend 60 minutes looking at:
- wallpaper
- sample furniture
- clubhouse
- swimming pool
- decorative lobby
Spend time checking things that cost money later.
Inspect:
- water pressure
- natural ventilation
- sunlight
- lift waiting time
- basement access
- parking dimensions
- fire exits
- construction quality
- seepage signs
- drainage
- approach road
- surrounding construction
- mobile network
- noise
For a ready property, ask residents:
“What is the biggest problem with this society?”
They will often tell you more in five minutes than the sales team tells you in an hour.
Step 5: Legal and Registry Checks
Before paying a substantial non-refundable amount, get independent legal verification.
For Gujarat property transactions, the government’s Revenue Department provides online services relating to land records, document registration and property cards.
Gujarat’s GARVI registration system also provides services connected with property registration, valuation and guideline/Jantri information.
Ask your lawyer to verify, as applicable:
- title
- ownership
- encumbrances
- development rights
- approved plans
- land-use status
- agreement for sale
- development permissions
- building permissions
- relevant NOCs
- RERA documents
- completion/occupancy documents for ready property
- previous title documents
- society/association documentation
Mistake to avoid
Do not treat:
“Bank has approved the loan”
as equivalent to:
“The property has no legal risk.”
The lender’s due diligence and your independent legal due diligence are not the same exercise.
Step 6: Negotiate the Property, Not Just the Price
This is where experienced buyers think differently.
If the seller refuses to reduce the headline price, negotiate:
- parking
- floor-rise charges
- maintenance
- furniture
- upgrade packages
- documentation charges
- payment schedule
- possession-linked payments
- other included items
Never negotiate emotionally
If the salesperson says:
“Last flat at this price.”
Ask:
“Please show me the written price breakup.”
If the offer is genuine, it should survive documentation.
Read More:- Legal Documents Every Home Buyer Should Verify
The Most Important Calculation: Total Cost of Ownership
Consider a hypothetical ₹80 lakh 3 BHK.
Your actual budget should look more like:
| Cost | Illustrative Amount |
|---|---|
| Flat price | ₹80 lakh |
| Down payment | ₹16 lakh* |
| Home loan | ₹64 lakh* |
| Stamp/registration & transaction costs | Calculate separately |
| Interiors | ₹5–10 lakh+ depending on specification |
| Appliances/furniture | ₹2–5 lakh+ |
| Maintenance/deposits | Project-specific |
| Emergency reserve | Keep separately |
Illustrative financing structure, not a guaranteed lender offer.
The exact statutory charges should be calculated using the applicable Gujarat government registration/valuation system and professional advice rather than copying a percentage from an old property blog. Gujarat’s GARVI system includes property valuation and registration-related services.
What About Tax Benefits on a Home Loan?
This is another area where buyers often hear incomplete advice.
For eligible taxpayers under the old tax regime, the Income Tax Department currently lists Section 24(b) interest deduction for a self-occupied property, subject to applicable conditions and limits; it also lists housing-loan principal under Section 80C within the combined ₹1.5 lakh limit.
But tax treatment depends on:
- property use
- tax regime
- loan purpose
- possession/construction status
- individual circumstances
- applicable law for the relevant assessment year
So don’t buy a ₹90 lakh property because someone tells you:
“You will save tax.”
A tax benefit should be a secondary consideration, never the reason a financially uncomfortable property becomes “affordable.”
Realistic Case Study
Realistic Case Study 1 — End-User Family
Illustrative example based on a common buyer profile; not a claimed real transaction.
Situation
A family with two working parents wanted a 3 BHK in Shela.
Combined monthly income:
₹1.75 lakh
Available savings:
₹28 lakh
They initially targeted:
₹90 lakh
Problem
After calculating the down payment, transaction costs, interiors and emergency reserve, they realised they would have very little cash left.
Instead of stretching to ₹90 lakh, they considered a property around:
₹76 lakh
Illustrative loan:
₹60 lakh
At an assumed 8.5% for 20 years:
EMI ≈ ₹52,000/month
Outcome
The family retained more liquidity and reduced the amount of borrowing.
Lesson
The important decision wasn’t finding the cheapest 3 BHK.
It was refusing to convert every available rupee of savings into property.
Realistic Case Study 2 — Investor
Illustrative example; not a claimed verified transaction.
An investor purchases a 3 BHK for:
₹72 lakh
Suppose the property generates:
₹25,000/month rent
Annual gross rent:
₹3 lakh
Gross rental yield:
₹3 lakh ÷ ₹72 lakh = approximately 4.2%
That is before:
- vacancy
- maintenance
- property tax
- repairs
- brokerage
- loan interest
- other ownership expenses
If the property later appreciates to ₹85 lakh, that does not automatically mean the investor made ₹13 lakh of profit.
Selling costs and the total financing cost matter.
What worked?
The investor bought at a price where the rental income provided some support.
What didn’t?
If the investor had borrowed heavily and depended entirely on rapid appreciation to justify the purchase, the investment would carry much greater financial risk.
Lesson
Do not call appreciation “profit” until you calculate the complete cost of ownership and exit.
Realistic Buyer Testimonials — Use Only After Verification
The following are sample testimonial formats, not genuine customer statements. Publish them only after obtaining permission from actual buyers.
IT Professional
“I originally focused only on the EMI. The bigger eye-opener was calculating the down payment, interiors and emergency fund together. That changed the property budget I was comfortable with.”
PSU Employee
“The site looked good during the first visit. We returned in the evening and checked the approach road and traffic. That second visit changed our shortlist.”
NRI Buyer
“The most useful part was having someone check the documents instead of relying on the builder’s sales presentation. I wanted a process I could verify remotely.”
Trust rule: Never publish these as real testimonials unless they come from real buyers who have consented to publication.
Current Market Context: Don't Confuse Asking Prices With Actual Values
One of the most important things to understand about Shela is the spread between listings.
Current Housing.com data shows a large number of 3 BHK listings and substantial variation in asking prices.
MagicBricks’ Q2 2026 data shows Shela apartment asking prices around ₹5,125/sq ft on average, with 3 BHK asking rates around ₹4,000–₹5,700/sq ft.
That variation is exactly why you should not ask:
“What is the Shela rate?”
Ask:
“What is the reasonable price for this exact project, carpet area, floor, age, condition, parking and location?”
A listing portal gives you an indication.
A registered transaction, legal due diligence and property-specific comparison give you stronger evidence.
Proofs & Screenshot Placements
Who This Guide Is NOT For
This guide is not designed for someone who wants to:
- flip a property in a few months
- buy purely because a broker says prices will rise
- depend on rumours about upcoming infrastructure
- purchase with almost no emergency savings
- maximise loan eligibility regardless of EMI
- buy only for tax benefits
- speculate on short-term appreciation
You should seriously reconsider buying now if:
Your down payment would consume almost all your savings.
Or:
Your EMI would leave you unable to maintain an emergency fund.
Or:
Your income is unstable and the property requires a large loan.
Or:
You are buying only because someone says:
“Prices will definitely increase.”
Nobody can guarantee that.
Renting may make more sense when:
- your job location may change
- you expect to relocate within a few years
- you haven’t identified the right micro-location
- your purchase requires excessive leverage
- you are still uncertain whether you want Shela for end use
Renting is not automatically “throwing money away.”
Sometimes rent is the price of flexibility while you avoid a bad purchase.
If I Were Buying This Property Today
If I were personally evaluating a 3 BHK in Shela today, I would not start by asking which project has the best amenities.
I would start with the financial structure.
I would shortlist a property only if:
- The total purchase cost fits comfortably within my income.
- I can make the required contribution without exhausting emergency savings.
- The RERA/project documentation checks out where applicable.
- An independent lawyer is comfortable with the title/documentation.
- I have compared at least several genuinely comparable properties.
- The actual carpet area works for my family.
- I can live with the location for several years even if prices remain flat.
Which configuration would I choose?
For an end-user family, I would focus on a practical 3 BHK with efficient carpet-area utilisation rather than simply buying the largest advertised super built-up area.
I would rather have:
a well-planned 3 BHK in a workable location
than:
a huge 3 BHK that looks impressive in the brochure but stretches the budget.
What would I negotiate hardest?
I would negotiate the total acquisition cost, not just the headline price.
I would ask for a written breakup covering:
- base price
- floor charges
- parking
- maintenance
- deposits
- documentation
- taxes/statutory charges
- other applicable costs
Then I would compare the final number with alternatives.
One red flag I would not ignore
Pressure to pay before I have completed document and financial checks.
“Today only.”
“Last unit.”
“Price increases tomorrow.”
“Other customer is waiting.”
None of those statements replaces due diligence.
If the property is good, it should still make sense after the paperwork is examined.
The Home Loan Checklist I Would Use Before Booking
Before paying a major booking amount, I would want these boxes checked:
Financial
- Total purchase cost calculated
- Down payment available
- Emergency fund preserved
- EMI stress-tested
- Existing loans considered
- Interest-rate reset understood
- Prepayment terms understood
Property
- Carpet area verified
- Price compared with similar properties
- Parking confirmed in writing
- Possession status verified
- Site visited more than once
- Approach road checked
- Water/drainage/infrastructure checked
Legal
- RERA record checked where applicable
- Title reviewed
- Agreement reviewed
- Relevant approvals checked
- Registration/valuation information checked
- Independent lawyer consulted
Exit
- Rental demand considered if investment
- Resale competition checked
- Future supply considered
- Holding period defined
- Exit costs considered
If several boxes remain unchecked, I would not rush into booking simply because the sales team is creating urgency.
Conclusion:
Buying a 3 BHK in Shela is not just a property decision.
It is a decision about:
- your monthly cash flow
- your savings
- your family
- your location
- your future flexibility
- and potentially 15–25 years of financial commitment
The biggest mistake is asking:
“How much home loan can I get?”
The better question is:
“How much home loan can I comfortably carry while still having a financially healthy life?”
Current Shela listings show that 3 BHK properties cover a broad pricing range, so there is no reason to treat one quoted project price as the market’s unquestionable value.
Check the property.
Check the project.
Check the documents.
Check the numbers.
Then make the decision.
If the numbers don’t work, walking away is also a successful outcome.
For buyers who want a practical starting point, a useful next step is to create a personal 3 BHK Shela Home Loan & Property Due-Diligence Checklist covering EMI, down payment, hidden costs, RERA, legal documents and site inspection.
Add Your Heading Text Here
Wait. What is WordPress?
How long do I get support?
Do I need to renew my license?
References
About the Author